We guarantee that No Pass No Pay
We are confident about our M05: Insurance law (IL) Exam test questions materials that we can help users pass real test certainly. Our passing rate for CII Insurance Law (M05) exam is 99.69%. Most candidates will clear exam successfully. We make sure that if you fail exam sadly we will full refund to you unconditionally. If candidates send us your unqualified score scanned, we will refund to you directly. Please trust our M05: Insurance law (IL) Exam test questions. If you choose us, we will help you success surely.
After purchase, Instant Download: Upon successful payment, Our systems will automatically send the product you have purchased to your mailbox by email. (If not received within 12 hours, please contact us. Note: don't forget to check your spam.)
Golden service: one year service warrant after sale
If you purchase our M05: Insurance law (IL) Exam test questions materials, we guarantee our products are valid for one year. You can download our latest materials free of charge within one year if we release new M05 test questions. If you are ready to purchase test engine, please rest assured that we will serve for ever user within one year before passing test.
How can you get valid M05: Insurance law (IL) Exam test questions for passing exam? Many candidates are looking for valid test online to pass exam day to day. Here is your chance. Testpassed offers the best high passing rate M05 test online to help candidates pass exam for sure. We are engaged in editing good test questions materials so many years. Our educational experts all have more than 8 years' experience in IT career certifications. Our M05: Insurance law (IL) Exam test questions are edited seriously and strictly. We guarantee our products help most of candidates pass test. If users pay much attention to our CII M05 test questions most of users will get good passing score.
Three versions of excellent products: PDF version, Soft version, APP version
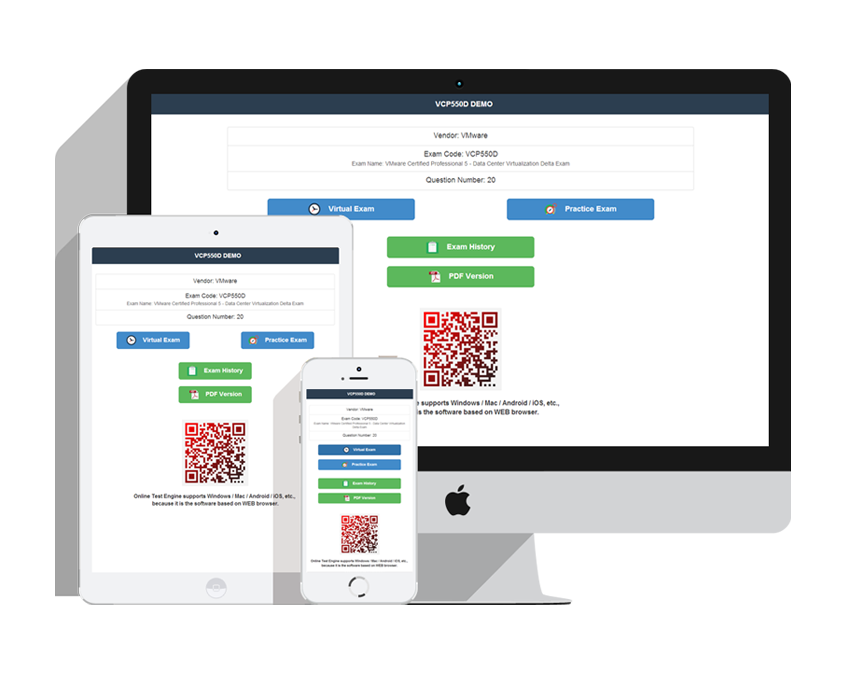
We release three versions of M05: Insurance law (IL) Exam test questions materials. Different kinds of products satisfy different demands of people. If you like writing and reading on paper, PDF version of M05 test questions are suitable for you. If you like studying on computer you can choose soft version or/and APP version.
These two versions of M05 test engine have some similar functions: timed test, mark your performance, point out wrong questions and remind you of practicing many times. Soft version of M05: Insurance law (IL) Exam test questions are downloaded and installed in personal computers (Windows operating system and Java environment). APP version of M05 test questions are based on WEB browser, it supports Windows / Mac / Android / iOS etc.
Soft version of M05: Insurance law (IL) Exam test questions can be downloaded in more than 200 personal computers. Once you download software, you use it offline any time. If there is no network, you can copy on another computer. APP version of M05 test questions are downloaded and installed well. It is based on web browser, if you do not close website, you can also use it offline. As to functional performance APP version of CII M05 test exam materials may be much stabler than Soft version.
Golden service: 7/24 online service support
We support 7/24 online customer service even on large official holiday. No matter when candidates have any problem & advice about M05: Insurance law (IL) Exam test questions materials we are sure to reply and solve with you soon. Service staff performance assess criteria are required that any email and contact about M05 test engine should be handled in two hours.
CII M05 Exam Syllabus Topics:
| Section | Objectives |
|---|---|
| Agency Law | - Creation and authority of agents
|
| Liability and Tort | - Employer and public liability
|
| Legal System and Sources of Law | - Structure of the legal system
|
| Insurance Claims and Legal Principles | - Claims handling principles
|
| Contract Law and Insurance Contracts | - Formation of contracts
|
CII Insurance law (IL) Sample Questions:
A married couple have equal shares in a property and are insured under a buildings insurance policy. What is the likely position in law of a breach of good faith by one party, which was unknown to the other party?
- A. Cover for both parties would be invalidated as the cover is likely to be a composite policy.
- B. Cover would be maintained in full for the innocent party as the cover is likely to be a composite policy.
- C. Cover would be maintained in full for the innocent party as the cover is likely to be a joint policy
- D. Cover for both parties would be invalidated as the cover is likely to be a joint policy.
Fran is self-employed and works from home. She uses her spare bedroom as an office and separately insures her computer, photocopier and other items of office equipment. She occasionally uses the equipment for personal use. Under the Consumer Insurance (Disclosure and Representations) Act 2012. in relation to insuring this equipment, she would be defined as a
- A. consumer because she is an individual.
- B. non-consumer because the items covered are not household items.
- C. consumer because she is working from home rather than on business premises.
- D. non-consumer because her insurance cover is mainly for business use.
Paul made a formal offer to John and gave hun (out weeks to accept it. Three weeks later, and before, John had responded. Paul needed to withdraw the offer. What is the position in contract law?
- A. John can enforce the contract as the offer was formally made.
- B. John cannot enforce the contract but is entitled to claim damages from Paul.
- C. Paul has the right to withdraw the offer at any time before acceptance.
- D. Paul does not have the right to withdraw the offer within the four-week period.
A household insurance policyholder leaves his home to go to work without setting the burglar alarm. Whilst he was out, his new tumble dryer overheats and causes fire damage to the kitchen. In what circumstances may the insurer legally reject a fire claim?
- A. If the tumble dryer is covered by extended warranty insurance.
- B. If there is a subrogation action against the manufacturer of the tumble dryer.
- C. If the policyholder exaggerates the value of the claim.
- D. If there is a breach of a warranty requiring the burglar alarm to be set.
What is the basis of settlement under a new for old insurance policy if a television is stolen?
- A. The replacement cost, less wear and tear.
- B. The original cost, less wear and tear.
- C. The replacement cost in full.
- D. The original cost in full.


 Janice

 Aubrey
 Sebastiane

 Dean
 Ivan
 Griselda

 Murphy
 Frederica
 Poppy
 Sid
 Ruby
 Wendy
 Stan